The story
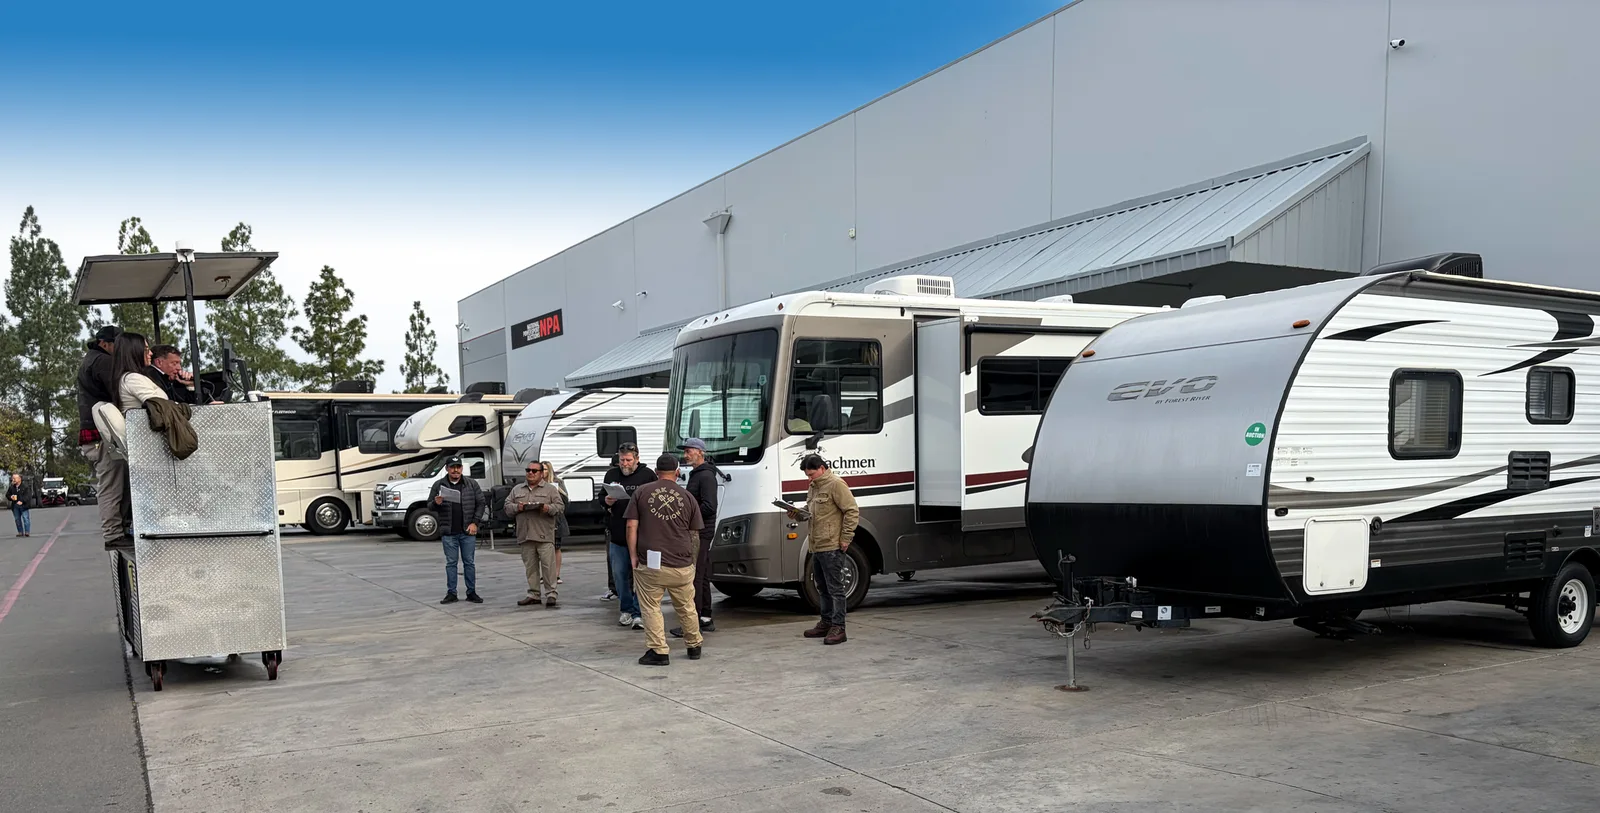
RVBusiness reported November 4, 2026, on National Powersport Auctions’ latest pre-owned RV report. The report says average wholesale prices for RVs and campers were 23% above year-earlier levels, while easing 6% from the preceding three-month average.
NPA and RVBusiness caution that the year-over-year increase should not be read as proof of accelerating demand. The gain occurred on thinner volume and a higher-value mix of units. In other words, the average price rose partly because the units changing hands were more expensive or more desirable, not necessarily because buyers were bidding aggressively across the entire used market.
The report also describes November as a predictable seasonal transition. Retail and wholesale traffic typically slow until spring, which can reduce transaction volume and make individual sales more influential in the average. Seasonal effects are especially relevant for truck campers, where buying activity is often linked to travel planning, regional weather, and the availability of tow vehicles.
For dealers, the combination of softer traffic and lower wholesale prices compared with the previous three-month period may create opportunities to acquire inventory selectively. The report suggests that used RVs can meet shoppers who are unwilling or unable to pay for new units. That dynamic is relevant to truck campers because a lightly used slide-in can offer access to a premium layout or equipment package at a lower entry price than a new model.
The report attributes continued used-market resilience partly to consumer sensitivity and higher fuel costs. Buyers seeking value may be more willing to consider a used camper, a smaller model, or a simpler pop-up instead of a new hard-side or high-capacity flatbed build. That could favor products with durable structures, common appliances, accessible replacement parts, and clear weight documentation.
The data does not isolate removable truck campers from other RV categories. It also does not provide model-level transaction counts, regional differences, retail prices, dealer margins, or the share of sales represented by slide-ins, flatbed campers, trailers, and motorhomes. Those limitations prevent direct conclusions about the health of the truck-camper segment alone.
Even so, the report provides useful market context. A higher average used price alongside lower recent-month pricing suggests a market where mix and timing matter more than a single headline number. Manufacturers may face pressure to justify new-camper prices through better warranties, more efficient power systems, lower weights, and stronger resale prospects. Dealers, meanwhile, may find demand among buyers who want truck-camper functionality but are delaying a new purchase.
The most meaningful follow-up will be whether used volumes improve as the spring buying season approaches and whether truck-camper values outperform or underperform the broader RV average. Until those data are available, the evidence supports cautious resilience rather than a confirmed recovery.
Why it matters
Used-market pricing affects new-camper demand, dealer inventory decisions, and resale expectations. The latest data suggests value-seeking remains important, but does not prove a truck-camper-specific rebound.